August 2026 Market Commentary
Market Update and Economic Developments
Financial markets navigated uncertainty successfully despite concerns over slowing job growth, geopolitical tensions, elevated interest rates, and signs that progress on inflation may be slowing. Markets were supported by a healthy consumer backdrop and another strong earnings season led by technology and AI-related companies. Nonetheless, future earnings growth into the final quarter of 2026 and first half of 2027 are now on investors’ minds with the S&P 500 range bound over the past 3 months.
Markets Push Higher Despite Mixed Economic Signals
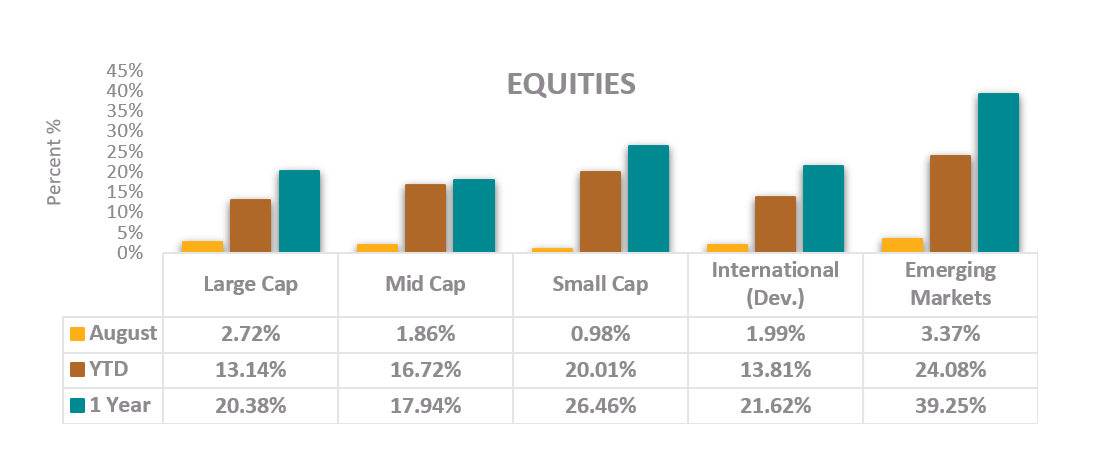
U.S. equities posted solid gains in August, with the S&P 500 rising approximately 2.7% and reaching new highs during the month. Investors were encouraged by strong corporate earnings, healthy consumer spending, and continued enthusiasm for AI-driven investment, helping offset concerns about interest rates and a slowing economy.
Market gains extended beyond mega-cap tech:
- U.S. Small-Caps: Participated in the rally as credit conditions remained stable.
- International Developed: Posted positive returns, boosted by improving earnings expectations and economic stabilization.
- Emerging Markets: Benefited from stronger global growth prospects and tech-sector tailwinds.
Corporate earnings remained broadly positive, with strength extending beyond technology into financials, healthcare, communication services, and consumer discretionary companies. Nvidia again reported record profit margins and net income while the forward Price/Earnings ratio has declined steadily this year. Investors are no longer impressed with Nvidia’s exponential growth. Overall, August reflected continued confidence in a soft-landing scenario in which economic growth and corporate profitability remain healthy despite inflation staying above the Federal Reserve’s target.
Fixed Income Market Update
Inflation: Progress Pauses
While inflation remains below cycle highs, recent data suggest progress has slowed. July CPI eased modestly to 3.4%, but Core PCE, the Fed’s preferred measure of underlying inflation, held steady at 3.3%. The data suggests that the final phase of returning inflation to more normal levels may prove slower and more challenging than earlier improvements. The Federal Reserve remains focused on ensuring inflation pressures do not become entrenched.
Labor Market: Cooling but Not Cracking
The labor market showed further signs of cooling in August, with employment growth and hiring activity continuing to moderate. While job creation remains positive, conditions are no longer as strong as earlier in the expansion. Even so, wage growth and household spending continue to provide support for overall economic activity.
Fixed Income Faces Headwinds
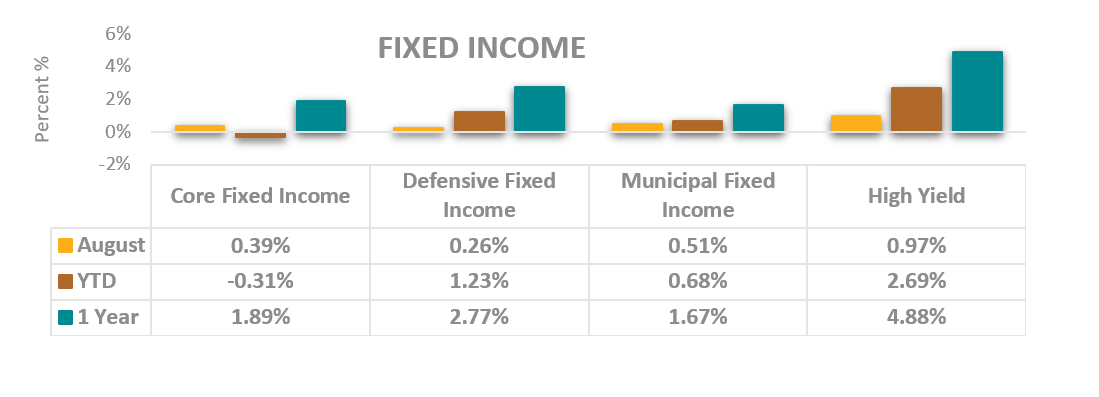
Bond markets faced pressure during the month as investors adjusted to the prospect that interest rates may remain elevated for longer than previously expected. Longer-dated Treasury yields remained relatively high, creating periodic volatility for longer-term bonds and other more interest-rate sensitive investments.
At the same time, elevated yields continue to provide attractive income opportunities across many segments of the fixed income market, particularly for investors focused on income generation and portfolio diversification.
Looking Ahead
Entering September, investors remain focused on several competing forces: a slowing but still expanding economy, moderating labor market conditions, healthy corporate earnings, and elevated market valuations. While risks remain, recent data continue to support the view that growth can slow without a significant deterioration in economic activity.
For long-term investors, August served as another reminder that markets often climb a “wall of worry.” The market’s story this year has been one of perseverance through uncertainty. While volatility will undoubtedly continue, the broader backdrop remains constructive, supported by healthy corporate profitability, continued technological innovation, and steady economic expansion.
Mission’s market and investment commentaries reflect the analysis, interpretation, and economic views and opinions of our investment team. They are not intended to provide investment advice for any individual situation. Please contact us if we can provide insight and advice for your specific needs.